

Employee Applicant Privacy Notice
Who we are:
Shape a brighter financial future with us.
Together with our members, we’re changing the way people think about and interact with personal finance.
We’re a next-generation financial services company and national bank using innovative, mobile-first technology to help our millions of members reach their goals. The industry is going through an unprecedented transformation, and we’re at the forefront. We’re proud to come to work every day knowing that what we do has a direct impact on people’s lives, with our core values guiding us every step of the way. Join us to invest in yourself, your career, and the financial world.
We are seeking an experienced Senior Manager, Credit Operations to build and lead SoFi Bank's specialized credit operations function across residential and Commercial loans. This role will oversee complex workflows across the credit lifecycle, including scenario intake, underwriting exceptions, condo and co-op project reviews, complex residential underwriting, and Commercial small-balance CRE underwriting and portfolio management.
This l functional owner will set the operating model, priorities, resourcing, service standards, KPIs, KRIs, and governance routines for the function. The Senior Manager will partner closely with Sales, Operations, Underwriting, Credit Policy and Administration, Risk, Product, Finance, Legal, Compliance, Servicing, and senior leadership to deliver sound credit judgment, scalable processes, clear accountability, and a consistent member and business-partner experience.
The ideal candidate is a seasoned credit leader with deep expertise in residential and commercial lending, particularly jumbo and portfolio underwriting, HNW and UHNW borrower profiles, complex refinances, and small-balance CRE underwriting and portfolio management. This is an opportunity to define an important capability at the intersection of credit judgment, operating design, policy, and member experience.
What you'll doBuild and lead the Credit Operations function
- Set the strategy, operating model, priorities, and service standards for specialized credit operations across residential and Commercial loans.
- Lead day-to-day planning, prioritization, intake, complexity tiering, routing, escalation paths, and decision ownership for scenarios, exceptions, complex underwriting, and project reviews.
- Establish KPIs, KRIs, reporting standards, operating routines, and quality expectations for volume, aging, cycle time, service levels, rework, exception trends, and capacity.
- Build the function in phases, using demand, complexity, service levels, quality, and outcomes to guide staffing, workforce planning, and future investment.
Lead complex residential underwriting scenarios and exceptions
- Oversee jumbo, portfolio, high-balance, high-LTV, and other non-conforming transactions, including complex refinances and cash-out refinance structures.
- Guide decisions involving HNW and UHNW borrowers, complex liquidity and reserves, asset depletion, RSU and equity compensation, self-employed and business income, complex tax returns, trusts or LLCs where permitted, and layered risk.
- Own the front door for residential scenarios from Sales and Operations, providing early guidance on credit viability, structure, documentation, risks, and likely escalation requirements.
- Operationalize exception reviews with clear intake requirements, recommendation packages, approval routing, decision tracking, and recurring-theme analysis.
Lead Commercial small-balance CRE underwriting and portfolio management
- Lead small-balance CRE underwriting and portfolio management across origination, credit administration, annual reviews, renewals, modifications, portfolio monitoring, and borrower management.
- Oversee borrower and guarantor analysis, property cash flow, leverage, debt service, liquidity, structure, collateral, repayment sources, and other core elements of small-balance CRE credit.
- Set quality and turnaround standards for deal preparation, financial statement spreading and analysis, annual reviews, renewals, modifications, and other portfolio-credit activities.
- Partner with Commercial relationship managers, the CRE Development team, portfolio managers, credit officers, and business leaders to improve submission quality, portfolio discipline, and borrower outcomes.
- Monitor portfolio performance, credit quality, concentrations, collateral trends, and emerging risks; escalate material credit, operational, compliance, or servicing matters promptly.
Lead condo and co-op project reviews
- Lead the specialized condo and co-op project review function when agency or government approval is unclear, lender review is required, or portfolio lending is being considered.
- Oversee documentation, eligibility, curability, risk evaluation, conditions, overlays, escalation recommendations, and decision tracking for non-warrantable projects.
- Create review standards, decision guides, checklists, training, and escalation triggers that improve consistency for Operations and Underwriting.
Connect Credit Operations to Credit Policy and Administration
- Create the feedback loop from scenario requests, exception themes, underwriting outcomes, and condo and co-op reviews into Credit Policy and Administration.
- Partner on guideline updates, overlays, decision guides, training, and implementation so operational learnings are incorporated into the broader credit framework.
- Capture recurring questions, ambiguous guidance, documentation gaps, and precedent themes; translate them into policy clarification, process improvements, product requirements, or targeted training.
- Maintain clear traceability from the initial request through the decision, escalation, policy response, and change-management outcome.
Partner across the business and develop the team
- Build trusted partnerships with Sales so complex borrowers receive timely, clear, and commercially practical guidance before significant origination effort is incurred.
- Partner with Operations and the second line of defense on intake quality, handoffs, service levels, documentation expectations, escalation triggers, and the routing of routine versus specialized work.
- Align with Credit Decisions and Insights, Product, Valuation, Default, Capital Markets, Servicing, Legal, Compliance, Finance, and other control partners when work crosses functions.
- Hire, coach, and develop a team that values disciplined judgment, constructive challenge, responsiveness, documentation quality, and shared accountability across Home Loans and Commercial.
- Lead responsible use of AI-enabled research and decision-support tools within a human-in-the-loop control model; use workflow data and recurring questions to improve knowledge and consistency.
- Deep experience in residential lending and commercial lending, including mortgage credit, secured lending, commercial real estate lending, commercial credit, portfolio management, underwriting, or credit administration.
- Strong understanding of jumbo and portfolio underwriting, complex refinances, high-LTV transactions, non-conforming credit, and specialized borrower profiles.
- Experience evaluating HNW and UHNW borrowers, including complex liquidity and reserve structures, asset depletion, equity compensation, self-employed income, complex tax returns, and layered risk.
- Experience leading small-balance commercial real estate underwriting and portfolio management, including borrower and guarantor analysis, property cash flow, leverage, debt service, liquidity, collateral, structure, and portfolio monitoring.
- Ability to solve highly complex credit and operational problems, exercise sound judgment in ambiguity, and make recommendations with clear rationale and disciplined escalation.
- Experience building operating models, managing workflows and resourcing, and developing KPIs, KRIs, credit quality metrics, portfolio reporting, and management-level updates.
- Strong understanding of bank credit policy, risk appetite, portfolio governance, regulatory expectations, audit readiness, controls, and consistent execution.
- Ability to influence senior leaders, Sales, Operations, Credit Policy, Underwriting, and control partners without relying solely on formal authority.
- Demonstrated experience leading teams through growth, process improvement, modernization, or operating-model change.
- Strong discipline around documentation, policy adherence, fair-lending awareness, governance, and responsible use of technology in credit decision support.
- 12 or more years of experience in residential mortgage underwriting, commercial lending, commercial real estate credit, credit risk, portfolio management, or a related financial services discipline, including at least 5 years of underwriting leadership or credit team management experience.
- Significant experience leading residential and commercial credit underwriting, portfolio management, credit administration, exceptions, scenario management, or a comparable specialized credit function, preferably within a regulated bank or financial institution.
- Deep experience underwriting or overseeing jumbo and portfolio transactions, including complex refinances and cash-out refinances.
- Experience evaluating HNW and UHNW borrowers and complex sources of repayment, liquidity, reserves, asset depletion, equity compensation, self-employed income, and layered risk.
- Experience leading small-balance commercial real estate underwriting and portfolio management, including deal preparation, financial statement spreading, annual reviews, renewals, modifications, and portfolio monitoring.
- Experience with condo and co-op project eligibility, non-warrantable projects, lender reviews, or portfolio project-risk assessment.
- Experience managing day-to-day operations, planning, prioritization, execution, resourcing, service levels, and capacity for a team or function.
- Experience modernizing credit policies, underwriting standards, operating procedures, reporting frameworks, controls, governance routines, or decision-support tools.
- Experience leading teams, developing talent, and managing individual contributors, specialized underwriters, analysts, portfolio managers, or other credit professionals.
- Familiarity with bank regulatory expectations, audit, loan review, fair-lending oversight, regulatory exams, credit loss forecasting, or enterprise risk management.
SoFi New York, New York, USA Office
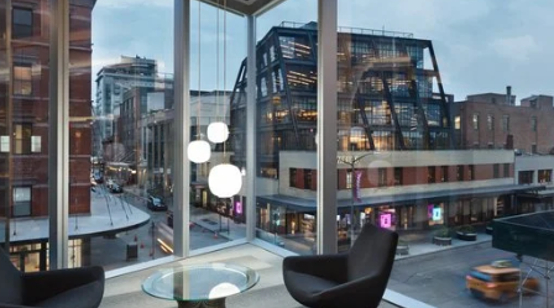

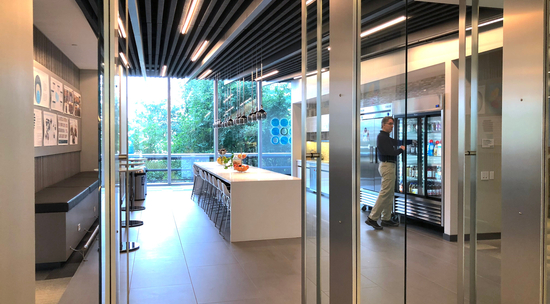
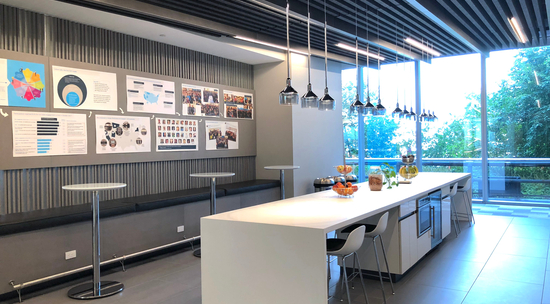
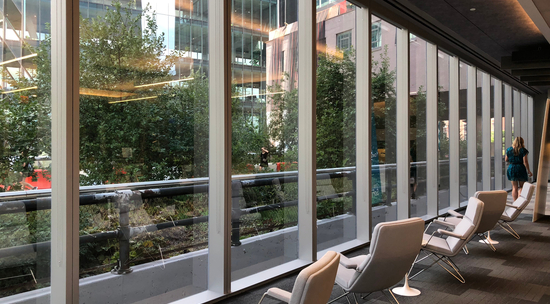
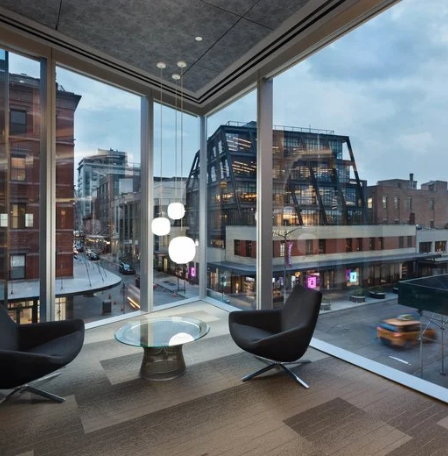

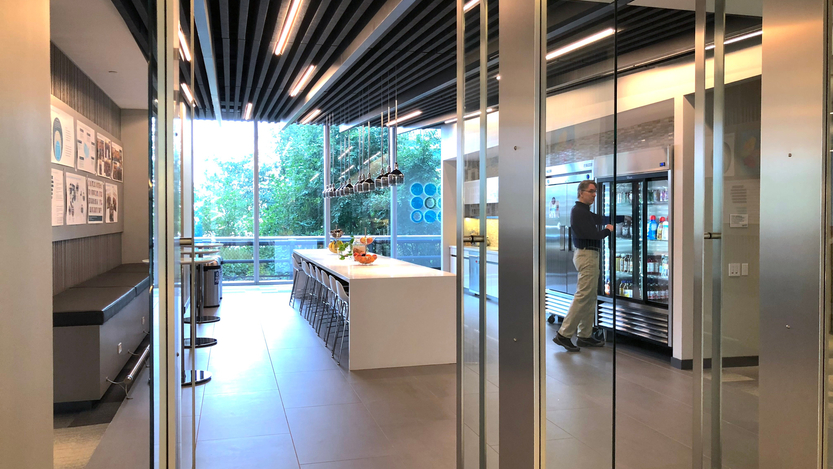
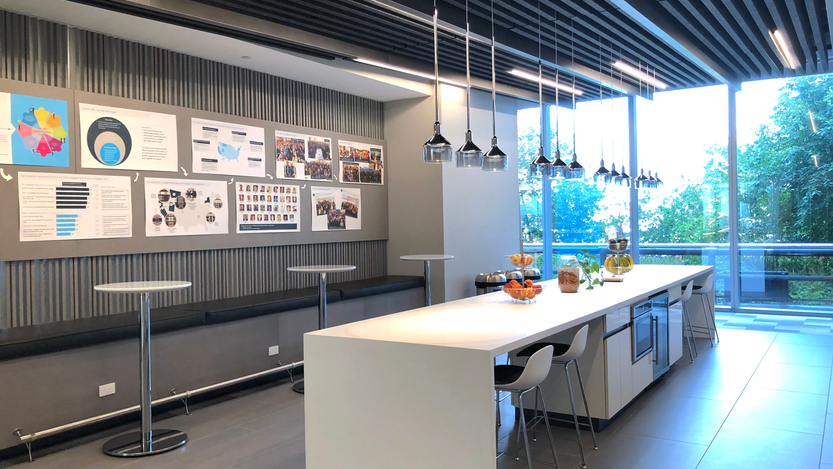
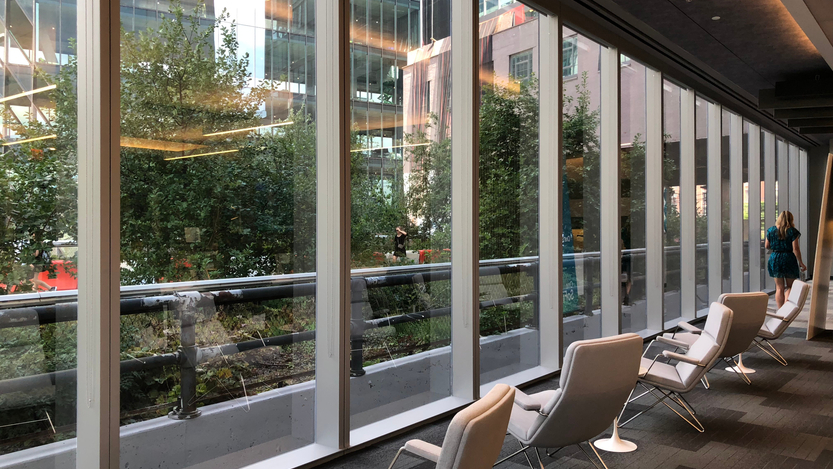
Our New York office, located in the meat-packing district, provides an open work environment and is a hub for our finance teams. Our large conference, flexible work spaces, huddle rooms, and shared community areas allows our teams to openly collaborate while looking at some spectacular views.
Similar Jobs at SoFi
What you need to know about the NYC Tech Scene
Key Facts About NYC Tech
- Number of Tech Workers: 549,200; 6% of overall workforce (2024 CompTIA survey)
- Major Tech Employers: Capgemini, Bloomberg, IBM, Spotify
- Key Industries: Artificial intelligence, Fintech
- Funding Landscape: $25.5 billion in venture capital funding in 2024 (Pitchbook)
- Notable Investors: Greycroft, Thrive Capital, Union Square Ventures, FirstMark Capital, Tiger Global Management, Tribeca Venture Partners, Insight Partners, Two Sigma Ventures
- Research Centers and Universities: Columbia University, New York University, Fordham University, CUNY, AI Now Institute, Flatiron Institute, C.N. Yang Institute for Theoretical Physics, NASA Space Radiation Laboratory
