

Top Cloud Companies in NYC, NY (361)
Xero is small business accounting software that provides a platform on which businesses can build a fully integrated solution. It’s designed to make life better for people in small business, their advisors, and communities around the world. Xero minimises tedious admin by automating routine tasks, delivers valuable insights when needed, and brings together business data, trusted advisors, and powerful apps...
Xero's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose 31% year over year to NZ$2.75–2.80 billion, alongside 37% AMRR growth and a 23% uplift in average revenue per customer. Customers increased 11% to about 4.92 million, reinforcing top-line momentum.
Healthy Cash Flow: Free cash flow reached NZ$554 million in FY26, increasing from the prior year. Adjusted EBITDA also grew 18% to NZ$757 million, indicating strong cash generation while scaling.
Market Expansion: Growth accelerated in the U.S. (including Melio payments) with continued double‑digit momentum in ANZ and the UK. Net additions of 506,000 in FY26 and a 4.92 million customer base highlight expanding regional reach.
Toast is the all-in-one platform built for restaurants of all sizes. Toast provides a single platform of software as a service (SaaS) products and financial technology solutions that give restaurants everything they need to run their business, including point of sale, payments, supplier management, digital ordering and delivery, marketing and loyalty, and team management. By serving as the restaurant operating...
Toast's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose about 23% year over year in Q2 2026 and 24% for full-year 2025, with ARR up 25% and GPV up 22% reinforcing a scaling top line. Guidance for 2026 recurring gross profit growth of roughly 23–25% further underpins momentum.
Profitability: Operating income and EPS roughly doubled year over year in Q2 2026 (operating income $152M vs. $80M; diluted EPS $0.26 vs. $0.13). Management also highlighted rising adjusted EBITDA and improved net income alongside recurring gross profit expansion.
Market Expansion: New offerings (e.g., Toast Drive‑Thru) and enterprise wins/expansions (e.g., Best Western, TGI Fridays UK, multi‑unit brands like Caribou Coffee and Potbelly) support broader adoption. The footprint reached about 180,000 total locations as of June 30, 2026, up roughly 22% year over year.

At New York Life, our 180-year legacy of integrity, mutuality, and financial strength fuels a future defined by bold transformation. As the largest mutual life insurance company in the U.S., we operate on behalf of our policy owners—not shareholders. That structure allows us to take a long-term view, investing in people, purpose, and innovation that endures. Guided by a clear enterprise vision...

New York Life's Top Stability & Growth Strengths
Profitability: Operating earnings reached a record $3.6 billion in 2025, up 4% year over year. Consecutive record years through 2024–2025 point to momentum in core earnings performance.
Investor Backing & Capital Strength: Total surplus rose to $34.7 billion in 2025 from $33.3 billion in 2024, and the company reports the highest financial strength ratings across A.M. Best, Fitch, Moody’s, and S&P. A record $2.8 billion dividend declared for 2026 further reflects balance‑sheet depth in a mutual structure.
Product Line Growth: Insurance sales increased 14% and annuity sales rose 40% in 2025, with mutual fund sales up 7%. Individual life insurance in force neared $1.3 trillion and AUM reached about $892 billion at year‑end 2025, indicating broad‑based expansion across offerings.
From solo developers building their first app to large enterprise teams if it needs to be fast, reliable, and beautifully built, it runs on Vercel. Our platform powers millions of deployments a day. We started with a simple belief: the web should be fast for everyone, everywhere. That belief became Next.js. Then a platform. Then the infrastructure layer for the...
Vercel's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is estimated to have risen from roughly $200M around May 2025 to about $340M by February 2026, indicating sustained double‑digit growth into 2026.
Investor Backing & Capital Strength: The company closed an oversubscribed $300M Series F on September 30, 2025 at a $9.3B post‑money valuation, alongside statements of 82% YoY top‑line growth and a doubled user base, with 2026 secondary references still around ~$8–9B.
Strong Market Position & Advantage: Next.js continues to see heavy adoption and rapid 2025–2026 releases, and Vercel has highlighted massive download growth over the prior year that tends to correlate with increased platform usage.
Monte Carlo is the agent trust platform that unifies data and agent observability to monitor, troubleshoot, and improve production AI systems. As enterprises prepare to deploy thousands of agents across business-critical use cases, Monte Carlo provides the reliability infrastructure to support them along this AI transformation, from human-guided agents to fully autonomous operations. Founded 2019. Backed by leading investors. Trusted...

Monte Carlo's Top Stability & Growth Strengths
Strong Market Position & Advantage: G2 has ranked Monte Carlo the #1 Data Observability platform for multiple consecutive quarters, and the company highlights enterprise wins such as Dell, American Airlines, Live Nation, and DraftKings. These signals point to prominent positioning in its category through 2025–2026.
Innovation-Driven Growth: Recent launches expand the platform from data observability into data + AI/agent trust, including Agent Observability, an Operations Agent, and unstructured data monitoring. New integrations and an EU hosting option broaden use cases and geographic reach.
Investor Backing & Capital Strength: A substantial Series D in 2022 at around a $1.6B valuation provides runway to invest through recent years. This capital base underpins expansion in product and go‑to‑market alongside visible enterprise traction.

In 1939, Bill Hewlett and Dave Packard, college friends turned business partners, started the original Silicon Valley startup in the space of a rented Palo Alto garage. Starting with audio oscillators, the friends built the foundation for a company that would grow to become a global leader in enterprise technology. More than 75 years later, our success is exemplified through...
Hewlett Packard Enterprise's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is at record levels with a strong year-over-year increase, and management has materially raised near‑term and next‑year growth outlooks on the back of robust Cloud & AI and Networking demand. Large order backlogs underscore momentum across core segments.
Profitability: Operating profit has expanded to record levels alongside stronger sales, and capital returns have increased. Management also signaled higher free cash flow for the year, pointing to improved margin and cash generation.
Strong Market Position & Advantage: The company is recognized as a Leader in key categories such as enterprise storage and wired/wireless LAN, and highlights sustained leadership in supercomputing. A broad global customer base and the GreenLake hybrid cloud platform reinforce competitive positioning across edge‑to‑cloud infrastructure.
Rubrik (NYSE: RBRK), the Security and AI Operations Company, leads at the intersection of data protection, cyber resilience, and enterprise AI acceleration. Rubrik Security Cloud delivers complete cyber resilience by securing, monitoring, and recovering data, identities, and workloads across clouds. Rubrik Agent Cloud accelerates trusted AI agent deployments at scale by monitoring and auditing agentic actions, enforcing real-time guardrails, fine-tuning...

Rubrik's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising rapidly across recent periods, with FY2026 results and the subsequent quarter both showing sharp year-over-year increases and strong subscription-led momentum. Management raised the FY2027 outlook following the latest quarter, underscoring continued demand.
Healthy Cash Flow: Free cash flow is meaningfully positive and improving at scale, including a healthy margin in Q1 FY2027 and a large year-over-year increase in FY2026. Improving subscription contribution margins indicate growing operating leverage.
Strong Market Position & Advantage: Independent analyst recognitions place the company among market Leaders for backup/data protection and cyber recovery, often highlighted for vision. Expanding large-customer cohorts and post-IPO scale further reinforce competitive standing.
We contribute to human progress by empowering people to express themselves, live in the moment, learn about the world, and have fun together.

Snap Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue accelerated to about $1.60B in Q2 2026, up 19% year over year, following 12% growth in Q1 2026 and an 11% increase for full-year 2025. Rising ARPU alongside expanding DAU/MAU supported this top-line momentum.
Healthy Cash Flow: Q2 2026 free cash flow reached roughly $121M and operating cash flow improved to about $176M, both sharply higher year over year. These gains indicate improved operating efficiency even as GAAP net income remains negative.
Diversified Revenue Streams: “Other revenue” driven by subscriptions like Snapchat+ grew ~85% year over year in Q2 2026 (after ~87% in Q1), and Snapchat+ surpassed 25M subscribers by mid‑2026. This diversification is complementing ad recovery and helping sustain growth.
Philo is a streaming television service that's reimagining the TV experience for the modern viewer. Founded by a group of technology and product enthusiasts, we set out to build the future of television by combining the best of modern technology with the most compelling medium ever invented—delivering the TV experience we've always wanted for ourselves. At our core, Philo provides an...

Philo's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue reached about $450 million in 2024, roughly 10% higher than 2023. This was disclosed alongside year-over-year subscriber growth in 2024.
Diversified Revenue Streams: Monetization spans subscriptions and advertising (about one-third of 2024 revenue), with FAST expansion positioned to grow ad sales even if paid subs plateau. The acquisition of ROW8 adds a TVOD rental stream slated for integration by early 2026.
Product Line Growth: The offering expanded with a free FAST tier and continued channel additions through 2026, plus new 2026 tiers (Essential at $25 and Bundle+ at $33). Earlier bundle changes such as adding AMC+ to the base plan broadened engagement and upsell paths.

Zscaler accelerates digital transformation so our customers can be more agile, efficient, resilient, and secure. Our cloud native Zero Trust Exchange platform protects thousands of customers from cyberattacks and data loss by securely connecting users, devices, and applications in any location.

Zscaler's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising briskly, with the latest quarter up year over year and full‑year FY2026 guidance raised for both revenue and ARR. Prior billings and deferred revenue growth indicate healthy demand heading into FY2026.
Strong Market Position & Advantage: Independent analyst evaluations place the company as a leader in SSE/SASE and note frequent inclusion on enterprise shortlists. A broad global footprint and regulatory certifications bolster competitiveness in regulated and international markets.
Product Line Growth: Expansion in newer offerings—such as Data Security, AI‑focused modules, and Zero Trust Branch—shows meaningful traction. Metered, non‑seat‑based solutions accounted for a sizable share of new ACV, suggesting broader monetization beyond core seats.
Cloudflare, Inc. (NYSE: NET) is the leading connectivity cloud company on a mission to help build a better Internet. It empowers organizations to make their employees, applications and networks faster and more secure everywhere, while reducing complexity and cost. Cloudflare’s connectivity cloud delivers the most full-featured, unified platform of cloud-native products and developer tools, so any organization can gain the...

Cloudflare's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising rapidly, with Q2 FY2026 results well above the prior year and management increasing the full‑year outlook while guiding continued momentum into Q3. These signals indicate sustained top‑line acceleration rather than a one‑off spike.
Resilient & Sustainable Growth: Contracted demand expanded, as current remaining performance obligations grew strongly in Q2 FY2026. Upmarket customer gains and elevated net retention further point to durable expansion from existing cohorts.
Innovation-Driven Growth: An AI/edge “inference layer” launch and ongoing Workers AI/Radar updates show active platform expansion and growing developer adoption. This product velocity positions the business to capture emerging AI‑driven workloads.
DISQO is a leading provider of advertising intelligence, measuring brand and performance outcomes across every media channel to power data-driven marketing decisions. Trusted by 500+ of the world’s largest brands and 150+ agency and media partners, and recognized by Inc., Deloitte, Ad Age, Digiday, Forbes, and Cynopsis, DISQO is redefining the power of measurement in advertising.
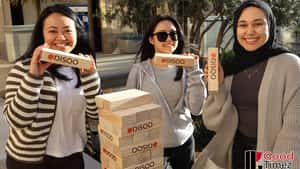
DISQO's Top Stability & Growth Strengths
Innovation-Driven Growth: Product launches such as AI Search Lift and ongoing rollouts of Brand Lift, Outcomes Lift, and cookieless measurement point to active R&D and continued expansion of capabilities.
Strategic Partnerships: Recent agreements with partners like DAX US for audio measurement and selections by large media owners (e.g., Comcast Advertising, Vevo, Warner Bros. Discovery) signal expanding distribution and commercial traction.
Future-Ready Strategy: Positioning around cross-platform, cookieless, and AI-aware measurement, alongside regular industry research and benchmarks, indicates alignment with post-cookie and AI-era advertiser needs.
Ericsson builds the digital connectivity the world relies on. Our technology underpins the mobile networks, platforms, and systems that billions of people, businesses, and societies depend on every day. We are a global leader in communications technology, delivering mobile network infrastructure, cloud software, and wireless connectivity solutions for service providers and enterprises worldwide. Our networks support connectivity across 180+ countries, helping...

Ericsson's Top Stability & Growth Strengths
Strong Market Position & Advantage: Industry assessments consistently position Ericsson as a top‑tier leader in 5G RAN and core, particularly outside China. Recognition by major analyst firms and marquee Tier‑1 wins point to durable competitive standing.
Cost & Operational Efficiency: Adjusted gross margins near the high‑40s and expanding Cloud Software & Services margins indicate effective cost discipline and mix improvements. Management has executed restructuring to lower the cost base amid rising component costs.
Investor Backing & Capital Strength: A strong net cash position and sizable shareholder returns (dividends/buybacks) were emphasized in Q2 2026. This financial flexibility supports navigation of a flat capex cycle and investment in IPR and enterprise initiatives.
As the AI platform for business transformation, we're putting AI to work across organizations — freeing people for work that matters. Making old tech work with new tech. Reaching across departments, from the front office to the back office and every office in between. Our ambition? To become the AI defining enterprise software company of the 21st century (or "AI...
ServiceNow's Top Stability & Growth Strengths
Strong Revenue Growth: Subscription revenue reached $3.877B in Q2 2026, growing strongly year over year, with total revenue also advancing. The company raised its full-year 2026 subscription outlook to $15.76–$15.78B and guided continued double-digit growth into Q3.
Product Line Growth: “ServiceNow AI” surpassed $1B in ACV in Q2 2026, acting as a catalyst for deal activity and upsell. Newer AI capabilities layered onto core workflows are described as adding incremental momentum.
Resilient & Sustainable Growth: Current and total RPO climbed to $13.20B and $29.0B, respectively, indicating strong contracted demand ahead. The number of customers above $5M in ACV increased meaningfully, supporting durable multi‑year expansion.
CoreWeave, the AI Hyperscaler™, delivers a cloud platform of cutting-edge software powering the next wave of AI. The company's technology provides enterprises and leading AI labs with cloud solutions for accelerated computing. Since 2017, CoreWeave has operated a growing footprint of data centers across the US and Europe. CoreWeave was ranked as one of the TIME100 most influential companies and...

CoreWeave's Top Stability & Growth Strengths
Strong Revenue Growth: Reported revenue rose from $1.9B in 2024 to $5.1B in 2025, with early‑2026 quarters continuing triple‑digit year‑over‑year increases. These disclosures indicate a steep, ongoing acceleration in scale.
Strategic Partnerships: Multi‑year, multi‑billion‑dollar agreements with Meta, Anthropic, Jane Street, and expanded OpenAI commitments point to durable, large‑scale utilization. A deepened NVIDIA collaboration, including early deployments of GB200/GB300 and plans to accelerate AI “factory” buildouts, supports access to cutting‑edge capacity.
Investor Backing & Capital Strength: Significant financing and market recognition—including a $1.1B Series C, large credit and notes facilities, and inclusion in the Nasdaq‑100—underscore strong capital access. This funding underpins rapid data‑center expansion and GPU procurement.

The database market is big. How big? Well, according to IDC, it’ll reach $153 billion by 2027. And MongoDB is at the forefront of that innovation with thousands of customers across the globe. We empower developers and businesses to build and deploy the applications they want, wherever they want.
MongoDB's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose 23% in FY2026 to about $2.46B, with Q4 FY2026 up 27% year over year and Q1 FY2027 up 25% year over year. Management guided FY2027 revenue to roughly $2.92–$2.96B, indicating continued double‑digit expansion.
Healthy Cash Flow: Operating cash flow reached about $505M in FY2026, and management highlighted “rule‑of‑40” performance in Q4. Recent updates also cite strong free cash flow in Q1 FY2027.
Innovation-Driven Growth: Atlas is the primary growth engine and reached roughly 73% of FY2026 revenue (about 75% in Q1 FY2027), with Atlas revenue growing around the high‑20s to ~30% year over year in recent periods. AI‑related additions such as vector search and Automated Embeddings (via Voyage AI) are positioned as catalysts for further adoption.
We're a global community of bold visionaries and resourceful doers who are shaping the future of Dropbox—and with it the future of work. Our Virtual First model combines the flexibility of a distributed workplace with the power of human connection, making space for both meaningful work and meaningful relationships. With our start-up mindset and enterprise-level opportunities, you can be who...

Dropbox's Top Stability & Growth Strengths
Profitability: Operating margins remain high, indicating sustained efficiency even as top‑line growth stays modest. Management commentary emphasizes maintaining strong margin discipline through 2026.
Healthy Cash Flow: Cash generation is robust, with sizable quarterly free cash flow and higher full‑year targets underscoring balance‑sheet flexibility. Capital returns and liquidity headroom support ongoing investment despite subdued growth.
Future-Ready Strategy: AI-led initiatives such as Dash and embedding intelligence into the core product signal a pivot toward next‑generation workflows. Ongoing rollouts and integrations point to a roadmap designed to reaccelerate growth over time.
.png)
NBCUniversal is one of the world's leading media and entertainment companies. We create world-class content, which we distribute across our portfolio of film, television, and streaming, and bring to life through our global theme park destinations, consumer products, and experiences. We own and operate leading entertainment and news brands, including NBC, NBC News, NBC Sports, Telemundo, NBC Local Stations, Bravo,...

NBCUniversal's Top Stability & Growth Strengths
Strong Revenue Growth: Peacock revenue rose to $1.9B in Q2 2026 (from $1.2B a year earlier) and to $4.0B in 1H 2026 (from $2.5B in 1H 2025), while the Studios segment delivered strong year-over-year gains with theatrical nearly tripling on new releases. This momentum indicates broadening top-line expansion across streaming and content.
Profitability: Peacock reported its first-ever quarterly profit in Q2 2026, aided by tentpole programming such as the Super Bowl, Winter Olympics, NBA on NBC, and FIFA World Cup coverage. Filings also point to EBITDA improvement within the Media unit that houses Peacock.
Market Expansion: Universal’s parks footprint expanded with Epic Universe opening in Orlando (May 2025) and the first Universal Kids Resort launching in Frisco, Texas (July 1, 2026). Local tourism-tax trends and the new attractions pipeline point to a multi-year parks-led growth opportunity.

With leaders boasting nearly two decades of experience working closely with Oracle NetSuite, ERP Success Partners possesses unparalleled expertise in harnessing the full potential of this powerful suite of applications to benefit our valued customers. Headquartered in Canada, our extensive geographic presence spans the United States of America, France, Mauritius, and the Philippines, enabling us to deliver exceptional value to...

Alight is a leading cloud-based human capital technology and services provider that powers confident health, wealth and wellbeing decisions for 36 million people and dependents. Our Alight Worklife® platform combines data and analytics with a simple, seamless user experience. Supported by our global delivery capabilities, Alight Worklife is transforming the employee experience for people around the world. With personalized, data-driven...
Alight Solutions's Top Stability & Growth Strengths
Strong Market Position & Advantage: Alight is positioned as a recognized leader with scale in U.S. health and welfare benefits administration, multi‑process HRO, and large‑plan DC recordkeeping, supported by recurring revenue and analyst validation.
Healthy Cash Flow: Cash generation and outlook are improving alongside margin expansion, with management highlighting better free cash flow guidance and delivery even as revenue has been soft.
Diversified Revenue Streams: The business is shifting toward higher-quality, platform-led revenue, with BPaaS growing and becoming a larger share of revenue while maintaining a largely recurring revenue base and meaningful revenue under contract.



